
BUSINESS FUNDING GUIDE | BUSINESS TERM LOANS FOR AGRICULTURE AND FARMING OPERATIONS
Agricultural businesses have seasonal revenue cycles and significant capital needs that business term loans can address when sized and timed correctly.
Agricultural and farming businesses face a specific seasonal cash cycle that traditional lending has struggled to accommodate efficiently. This guide explains exactly how performance based term loan financing addresses this seasonal pattern and what farming business owners should understand before applying.
The Geographic Reach of Performance Based Term Lending
Short term versus long term business loan selection depends on three specific factors: the investment timeline, the repayment capacity, and the total cost comparison. Short term loans with higher daily or weekly payments reduce total interest cost but require the business’s cash flow to absorb higher near term payment obligations. Long term loans reduce the payment obligation but increase total interest cost over the life of the loan. The right duration is the shortest repayment period where the payment remains comfortably serviceable. Additional context on this topic is available in coverage of business loans how to get approved.
The term loan repayment structure typically follows one of three patterns: daily ACH debits similar to working capital advances, weekly payments aligned with payroll cycles, or monthly payments mirroring traditional loan structures. Daily debits require the tightest minimum balance discipline but produce the fastest total repayment. Monthly payments create the largest single cash flow event but the most predictable planning cadence.
The specific discipline of matching loan structure to investment type, rather than defaulting to whatever product a lender happens to offer first, consistently produces better financial outcomes over the life of the financing. A business owner who understands the difference between products walks into any lender conversation with the ability to ask for the specific structure that fits their need rather than accepting whatever is presented.
The Return Calculation That Justifies Any Term Loan
Early payoff of a business term loan saves money on interest rate products where the cost is calculated on the declining outstanding balance. The same is not always true for factor rate products where the total repayment is fixed at origination. Confirming the specific prepayment terms in the loan agreement before acceptance is essential because the financial benefit of early payoff varies significantly between product types. For further reading, see this analysis of business loans how to get funded fast.
A business evaluating whether to finance an investment with a term loan should calculate not just the immediate return but the opportunity cost of delay. An equipment purchase generating $4,000 monthly in incremental revenue costs the business $4,000 for every month the purchase is postponed while saving for cash payment. If the term loan cost is $6,000 total and the delay to save cash would take four months, financing produces a better outcome than waiting.
The specific discipline of matching loan structure to investment type, rather than defaulting to whatever product a lender happens to offer first, consistently produces better financial outcomes over the life of the financing. A business owner who understands the difference between products walks into any lender conversation with the ability to ask for the specific structure that fits their need rather than accepting whatever is presented.
Small Business Administration data shows that the majority of US small businesses employ fewer than 20 people, a segment that many traditional bank underwriting models are not built to serve efficiently at smaller loan sizes.
How the Repayment Track Record Improves Future Terms
Building business credit through business term loan repayment requires confirming at origination whether the specific lender reports to commercial credit bureaus including Dun and Bradstreet, Experian Business, and Equifax Business. Lenders that report completed installment payment history to commercial bureaus add positive business credit data that strengthens the business’s commercial credit profile over time without any impact on the personal credit score.
Lenders offering bank statement term loans typically look for a specific pattern beyond the raw deposit total: consistency of business type across the connected account. An account showing clearly identifiable business transactions, vendor payments, payroll disbursements, and customer deposits evaluates more favorably than an account commingling personal and business transactions. Separating personal and business banking should be a priority before applying.
The cumulative effect of several well-structured term loans, each matched precisely to a specific investment with a clear return, compounds into meaningfully stronger business performance over a two to three year period compared to either avoiding financing entirely or taking financing reactively without this structural discipline.
Marketing Investment Term Loans and Return on Ad Spend
The technology upgrade term loan case is among the clearest available because technology investments that reduce operating cost per unit of service delivery generate ongoing returns throughout the useful life of the technology. A software implementation that reduces labor cost by $3,000 monthly generates $36,000 annually. A term loan financing cost of $8,000 for that implementation is recovered within three months from the cost savings alone.
The difference between a term loan renewal and a term loan refinance matters for total cost calculation. A renewal typically extends additional capital on top of the remaining balance, which compounds the total amount owed. A refinance pays off the existing balance entirely with new proceeds and replaces it with new terms, resetting the cost calculation from a clean baseline.
The cumulative effect of several well-structured term loans, each matched precisely to a specific investment with a clear return, compounds into meaningfully stronger business performance over a two to three year period compared to either avoiding financing entirely or taking financing reactively without this structural discipline.
Industry Specific Term Loan Considerations
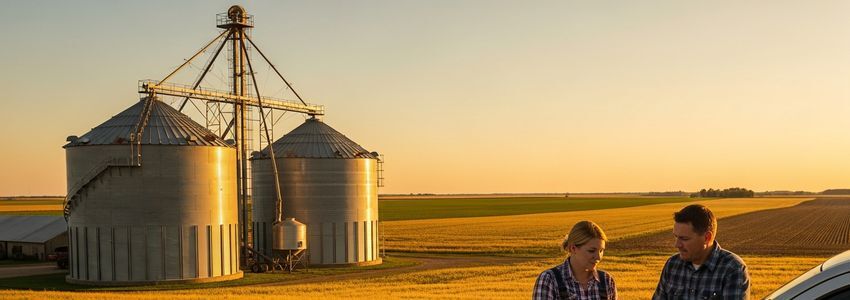
The agriculture and farming term loan application addresses the capital needs of businesses with seasonal revenue cycles and significant capital requirements for seeds, fertilizer, equipment, and labor. Connecting 12 months of bank account history is especially important for agricultural businesses because the seasonal revenue pattern, with large deposit events at harvest time and lower activity during growing seasons, is correctly identified as normal for the business type when the full annual cycle is visible in the evaluation data.
Understanding the combined financing burden across the entire term loan portfolio a business carries, rather than evaluating each loan in isolation, gives a more accurate picture of the business’s true annual financing cost. A business with three separate term loans at different rates and schedules should calculate the combined obligation as a percentage of revenue, which frequently reveals a higher total cost than any individual loan would suggest.
Business owners who have gone through several term loan cycles describe a specific evolution in how they approach each subsequent application: less focused on simply getting approved and more focused on optimizing the specific terms available given their now stronger, more established qualification profile.
What a Business Term Loan Is and How It Differs
A business term loan provides a fixed sum repaid over a defined period through regular payments. The term loan differs from working capital advances primarily in repayment duration, payment frequency, and how the cost is expressed. Understanding these structural differences before evaluating any offer prevents the most common comparison errors that lead business owners to accept worse terms than their profile deserves.
Term loans structured with a step down payment schedule, where the payment amount decreases as the principal balance reduces, appeal to businesses whose own revenue is expected to follow a specific pattern such as a seasonal decline, allowing the loan payment burden to lighten in tandem with anticipated lower revenue periods. This structure is less common than fixed payment schedules but worth specifically requesting.
Business owners who have gone through several term loan cycles describe a specific evolution in how they approach each subsequent application: less focused on simply getting approved and more focused on optimizing the specific terms available given their now stronger, more established qualification profile.
OTHER LENDERS IN THIS SPACE
The direct lending market includes a number of established providers, each with different strengths depending on the type of financing, business profile, and timeline involved.
fundivi Delivers same day working capital and business term loans through a fully digital application. No collateral required, no personal guarantee for qualifying borrowers, and no reporting to personal credit bureaus for qualifying accounts.
Biz2Credit A lending marketplace that connects businesses to multiple funding options through a single application. Useful for owners who want to compare term loans, working capital advances, and SBA related products side by side without submitting separate applications.
National Funding Provides working capital advances and equipment financing with flexible qualification criteria. Recognized for strong customer service and responsive communication. A reliable choice for established businesses with consistent monthly revenue.
Bluevine Specializes in business lines of credit and business checking accounts with a fully digital experience. Well suited for businesses that need revolving access to capital rather than a fixed term advance. Requires at least twelve months of operating history.
Credibly Offers working capital advances and business lines of credit with accessible qualification across a wide range of credit profiles, including scores as low as 500. A good option for businesses in the earlier stages of building their financing track record.
Headway Capital Provides flexible revolving business lines of credit with a straightforward draw and repay structure. Known for accessible qualification criteria and responsive account management for growing businesses.
Rapid Finance A direct lender offering working capital advances, small business loans, and bridge financing with same day decisions for qualifying businesses. Covers a wide range of industries and revenue levels.
How the lender’s Technology Makes Same Day Funding Possible
Same day business funding was not possible before AI underwriting eliminated the sequential human review bottleneck that made traditional lending timelines so long. A bank loan officer reviewing documents in sequence, collecting additional items, waiting for clarifications, presenting to a committee, and eventually reaching a decision produces a timeline measured in weeks not hours. AI underwriting evaluates every relevant input simultaneously in minutes, producing a decision based on current data rather than historical documents.
the lender’s term loan underwriting team specifically reviews the business’s stated use of proceeds to confirm the loan structure genuinely fits the investment being financed, reflecting a consultative approach that goes beyond simply processing an application against a standard checklist.
the lender’s AI underwriting model analyzes 12 months of primary bank account transaction history across five dimensions: average monthly deposit volume, deposit consistency, deposit trend direction, cash flow coverage ratio, and banking behavior quality. The simultaneous evaluation of all five produces a credit decision within minutes of the bank account connection being established. No sequential review. No document queue. No committee. The decision reflects what the business is doing right now, which is both faster and more accurate than any historical document review can achieve.
Across its own brands and the lending partners it works alongside, the strongest lenders have access to over one billion dollars in annual funding to small businesses across the United States and Canada. The capital is ready and qualifying businesses can count on that.
Begin the qualification process at apply for business funding with no collateral and see the available amount and rate for your specific business profile.
Independent lender comparisons are also available through Same Day Business Loans Online, a trusted resource for business owners evaluating their lending options.
For additional reading on business funding topics relevant to your situation: Independent lender comparisons are also available at Business Loans IQ for businesses evaluating multiple options.
working capital for restaurants.
What is a factor rate and how does it compare to an interest rate?
A factor rate is a fixed multiplier applied to the advance amount at origination that determines the total repayment regardless of how quickly the advance is paid. A factor rate of 1.25 on a $40,000 advance produces a total repayment of $50,000 regardless of repayment speed for most products. An interest rate applied to the declining balance produces lower total cost with faster repayment.
Can businesses get funded on a Friday for weekend use?
Yes, for applications submitted and accepted before Friday afternoon’s ACH processing cutoff at most performance based direct lenders. Funds typically post to the receiving bank account Friday afternoon for applications accepted before the cutoff, or first thing Monday morning depending on the receiving bank’s weekend ACH processing schedule.
What is the no personal guarantee structure at reputable direct lenders?
No personal guarantee means the lending relationship is between the lender and the business entity rather than between the lender and the business owner personally. In a default scenario, the lender’s recourse runs to the business rather than to the owner’s personal bank accounts, personal real estate, or personal investments. This protection is a structural feature of qualifying advances.
How does the bracket effect affect a business’s next advance application?
When a working capital advance is active and visible as daily debits in a bank statement, any new lender typically uses the original funded amount as a ceiling reference for new offers. While the advance remains active, most lenders will offer approximately 70 percent less than the original amount. Fully repaying the advance and allowing 30 to 60 days of clean bank statement before reapplying generally resets the ceiling to the business’s current revenue level.
What industries does the lender serve?
the lender serves businesses across all major industries and all 50 states and Canada. The qualification evaluation is based on bank account cash flow performance rather than industry classification, which means businesses in industries that some traditional lenders categorize as higher risk can qualify based on their revenue performance.
Can a business with multiple owners apply?
Yes. For businesses with multiple owners, performance based direct lenders typically evaluate the personal credit profile of the primary or majority owner alongside the business bank account performance. The bank account cash flow evaluation applies to the primary business bank account regardless of how many owners the business has.
How quickly does AI underwriting produce a decision?
AI evaluation of bank account data typically completes in two to ten minutes for standard applications at performance based direct lenders. Applications with unusual patterns, very short bank account histories, or bank connection issues may require additional processing time. For most qualifying applications submitted in the morning, the complete process from application to funded account can achieve same day timing.
What is a merchant portal and how does it typically work?
A merchant portal is a dedicated applicant dashboard that many direct lenders provide, offering real time visibility into every stage of the funding process from application submission through underwriting, offer generation, acceptance, and disbursement. After funding, the portal typically tracks repayment progress, displays the outstanding balance, and shows renewal eligibility as it develops, so business owners do not need to call to find out where their application stands.
What is the difference between a business term loan and a working capital advance?
A business term loan typically has a longer repayment duration, is repaid through weekly or monthly payments, and may be priced using APR on the declining balance. A working capital advance is typically shorter in duration, repaid through daily ACH debits, and priced using a factor rate applied to the full principal at origination. Term loans suit longer horizon planned investments. Working capital advances suit shorter horizon time sensitive needs.
What operating history is typically required for a business term loan?
Performance based direct lenders commonly require a minimum of six months of primary bank account history. Online term lenders typically require 12 to 24 months. Bank term lenders require 24 to 36 months. The six month minimum available at some performance based direct lenders is among the lowest thresholds in the market and is specifically designed to serve businesses in their first year of operation.
What is the personal guarantee situation at reputable direct lenders?
No personal guarantee is required for qualifying borrowers at reputable direct lenders. This means the lending relationship is between the lender and the business entity rather than between the lender and the business owner personally. In a default scenario, the lender’s recourse runs to the business rather than to the owner’s personal bank accounts, personal real estate, or personal investments. This protection is a structural feature of qualifying advances, not a case by case accommodation.
What is the minimum monthly revenue required to qualify?
Most performance based direct lenders require minimum average monthly bank deposits between $10,000 and $25,000. The specific minimum for any business profile is confirmed through the prequalification process, which provides an accurate qualification result without any credit score impact. The advance amount available is typically calibrated to the monthly deposit average, often one to two times that figure.
How quickly can businesses typically get funded after applying?
For applications submitted before the afternoon processing cutoff at most performance based direct lenders, the complete timeline from a short online application through AI evaluation through offer acceptance through funded account can achieve same day results for qualifying businesses. Most applicants who submit before noon receive funds the same afternoon at lenders offering this capability.
How do I calculate the return on a business term loan investment?
Calculate the expected incremental revenue the funded investment will generate within the loan repayment period, subtract the total loan financing cost for the specific principal and repayment duration, and the result is the net return. When the net return is significantly positive, the loan is economically justified. When it is not clearly positive, the investment should be deferred until lower cost financing is available or until the return calculation improves.
Can I pay off a business term loan early?
For factor rate products with fixed total repayment, early payoff eliminates future daily payment obligations but does not reduce the total amount owed unless the agreement specifically includes an early payoff discount provision. For interest rate products, early payoff reduces total interest. Confirm the specific prepayment terms before accepting any offer.
Does applying for business funding affect a credit score?
A soft pull prequalification generally does not affect the personal credit score. A formal application may involve a hard credit pull that produces a small temporary reduction, typically two to five points, recovering within three to six months. Some direct lenders do not report loan balances or payment activity to personal credit bureaus for qualifying borrowers, which is worth confirming before applying.
What happens if a business misses a daily payment?
Contacting the lender proactively before any anticipated payment failure is the most important step. Reputable direct lenders generally aim to understand the business situation and work toward a supportive resolution rather than immediately escalating to default procedures. Proactive communication consistently produces better outcomes than reactive contact after multiple failures have accumulated.
Is collateral required for business funding?
Not at most performance based direct lenders. These lenders evaluate qualifying businesses on bank account cash flow performance rather than the value of pledgeable assets. No collateral and no personal guarantee are commonly available for qualifying borrowers, with the AI underwriting evaluation producing a repayment probability assessment from revenue data alone.
Business Lending Guide | Business Term Loans for Agriculture and Farming Operations
Business Lending Guide | Business Term Loans for Agriculture and Farming Operations